
Frequently Asked Questions About Credit Card Processing in Long Beach, New York
What are the main options for credit card processing for small businesses in Long Beach?
Most businesses choose between a traditional merchant account, a payment service provider (PSP), or a mobile/card-present and card-not-present setup. Card-present options use countertop terminals, while e-commerce typically uses payment gateways and checkout integrations. If you take payments in person and online, ask how the provider supports both. Also confirm whether they handle setup for your specific sales channels, such as online invoices or recurring billing, and how you’ll receive monthly reporting for reconciliation.
How do I reduce credit card processing fees and avoid unexpected charges?
Start by understanding what drives your total cost: transaction type (swiped/chipped vs. keyed), interchange categories, and any add-on fees from the provider. Request a clear fee schedule and review how chargebacks, refunds, and payment disputes are billed. If you process more in-person than online, choose equipment and settings that maximize chip and contactless. Regularly audit your statements to spot unusual surcharges, minimums, or tier changes and confirm policies with support.
What’s the difference between card-present and card-not-present processing?
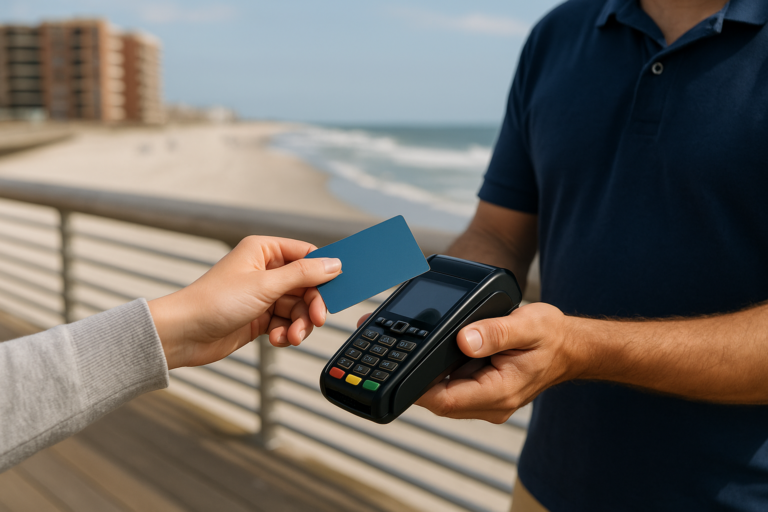
Card-present processing happens when the customer physically presents the card—such as swiping, inserting a chip, or tapping contactless. Card-not-present processing occurs when the card isn’t physically present, like phone orders or online transactions. Typically, card-not-present payments have different risk controls and may cost more due to fraud exposure. If you offer online sales or take orders by phone, ensure your setup includes fraud tools and a secure checkout flow rather than relying on manual entry.
Do I need a payment gateway to accept online credit card payments?
In many cases, yes. A payment gateway securely captures payment details and connects your checkout to the processing system. Some providers bundle the gateway with their platform, simplifying setup, while others require you to integrate a gateway with your e-commerce or invoicing software. When choosing, consider whether you need features like tokenization (to reduce exposure of sensitive data), recurring payments, and support for the platforms you use. Ask how refunds and chargebacks flow back into your system.
How should I handle chargebacks and payment disputes when using credit card processing?
Chargebacks are initiated when a cardholder contests a transaction. To manage them effectively, keep documentation that supports the sale—such as receipts, proof of fulfillment for online orders, and customer communication records. Make sure your refund and cancellation processes are consistent and easy to audit. Many processors offer dispute tools in the merchant dashboard; review the timeline and required evidence so you can respond promptly and accurately. If you’re unsure what qualifies, ask your processor for dispute guidance.