
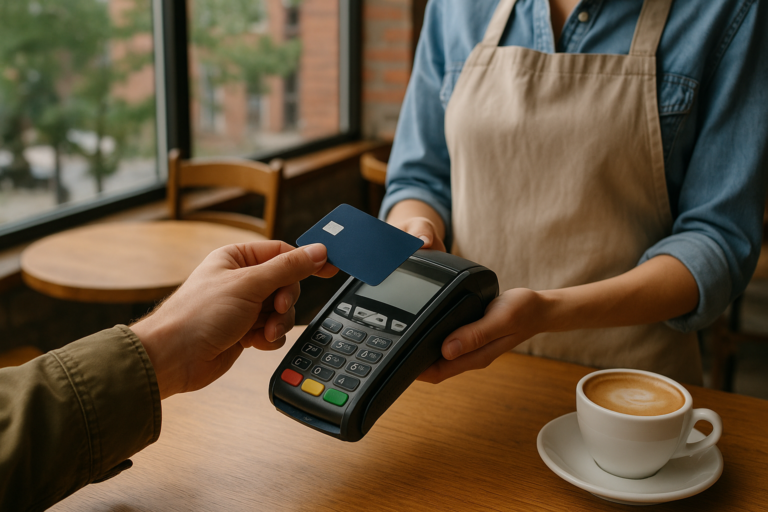
Frequently Asked Questions About Credit Card Processing in Beattystown, New Jersey
What payment types can I accept with credit card processing?
Most credit card processing solutions support common card types like Visa and Mastercard, and many also handle debit cards and contactless payments (such as tap-to-pay), depending on the terminal or provider. If you’re running a business in Beattystown, NJ, ask about compatibility with the equipment you already use (POS system, card reader, or online checkout). Confirm whether you need card-present transactions only, card-not-present (online/phone) capabilities, or both.
How does the credit card transaction process work for my business?
When a customer pays by card, the transaction is captured by your POS or payment terminal and sent through your payment processor for authorization. The processor checks the card’s available funds with the card network and the issuing bank. If approved, the payment is confirmed to your system and later settled to your business account after the batch/settlement cycle. Your reporting typically shows approvals, declines, and refunds.
What fees should I expect for credit card processing?
Credit card processing usually involves multiple fee components, such as per-transaction fees, possible monthly charges, and network or interchange-related costs. The exact structure depends on how you accept payments (swiped/tapped vs. keyed-in, in-person vs. online) and your business volume. To avoid surprises, request a clear fee schedule and ask which charges apply to refunds, chargebacks, or higher-risk transactions. Ensure you can read statements and reporting easily.
Can I accept credit cards for both in-person sales and online orders?
Yes—many businesses use a combination of terminal-based processing for in-person transactions and an online payment option for e-commerce or invoices. The key is making sure your payment setup supports the channels you use: card readers for storefront sales and a compatible online checkout or payment link for remote orders. If you already have a website or POS, ask whether integration is straightforward and whether you can manage refunds and reconciliation in one place.
What happens if a customer disputes a charge (chargeback)?
A chargeback happens when a cardholder disputes a transaction with their bank. When it occurs, you may receive evidence requests to support the purchase—such as receipts, authorization details, proof of delivery, or communication records, depending on the reason. Good processing workflows help: keep accurate transaction records, use clear policies, and ensure refunds are handled properly. Ask your processor what documentation you’ll need and how disputes are communicated so you can respond effectively.