
Frequently Asked Questions About Credit Card Processing in East Patchogue, New York
What’s the difference between a credit card terminal, a payment processor, and a merchant account?
A credit card terminal is the device used to swipe, dip, tap, or read cards. A merchant account is the type of banking setup that allows you to accept card payments and handle the flow of funds. A payment processor is the company that routes transactions between the terminal, the card networks, and the bank. Many local businesses choose a combined provider for simpler billing and support, but it’s still helpful to understand the roles involved.
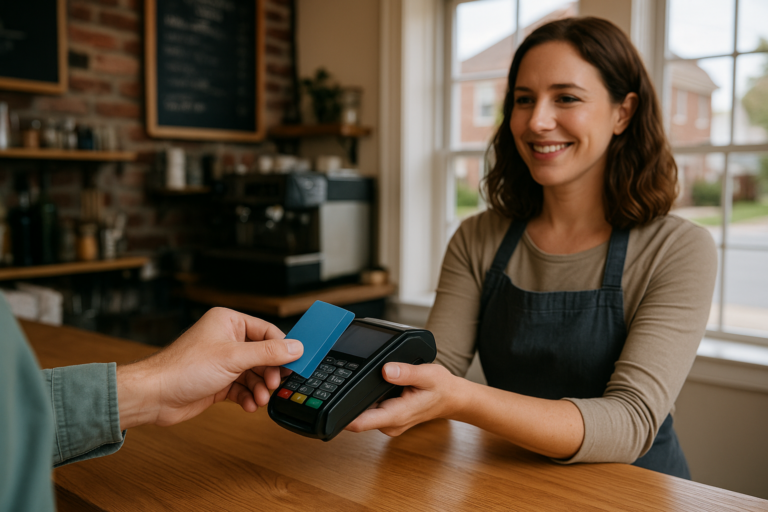
Do you support contactless payments and EMV chip cards for in-person transactions?
Yes—reputable credit card processing solutions typically support the payment methods used for modern cards, including contactless “tap-to-pay” and EMV chip transactions. For contactless, you’ll typically use an NFC-enabled terminal. For chip cards, the terminal prompts the cardholder to insert and follow on-screen steps. If you’re currently using older equipment, a provider can review what’s needed for chip compliance and contactless acceptance.
What information do I need to start accepting credit cards for my business?
Most onboarding requires basic business details and compliance-related information. Expect to provide ownership or business verification, your legal business name, tax details, and contact information for the account. You’ll also need details about how you’ll accept payments—such as in-person only, online, or both—and your expected transaction volume. A good processing setup also asks how you want to handle receipts, payment types, and reconciliation so your accounting can match deposits accurately.
How do fees work, and what should I watch out for on my statement?
Credit card fees often include a mix of processing rates and additional charges. The most common elements include per-transaction charges, percentage-based fees, and sometimes monthly platform or gateway fees depending on your setup. Some providers also charge for specific services such as chargeback handling or extra reporting tools. The key is to review whether fees vary by card type, whether online and in-person rates differ, and how deposits are netted so you can reconcile payments to bank activity.
If a customer disputes a charge, how are chargebacks handled?
When a customer disputes a card purchase, the issuing bank opens a chargeback. To respond, you’ll need transaction records such as proof of authorization, sales documentation, and any supporting policies that show how the purchase was handled. A strong processing arrangement includes clear guidance on what evidence to gather and how to submit it through the card network’s timelines. Ask about how chargeback notifications are delivered and what reporting tools help you identify transactions quickly.