
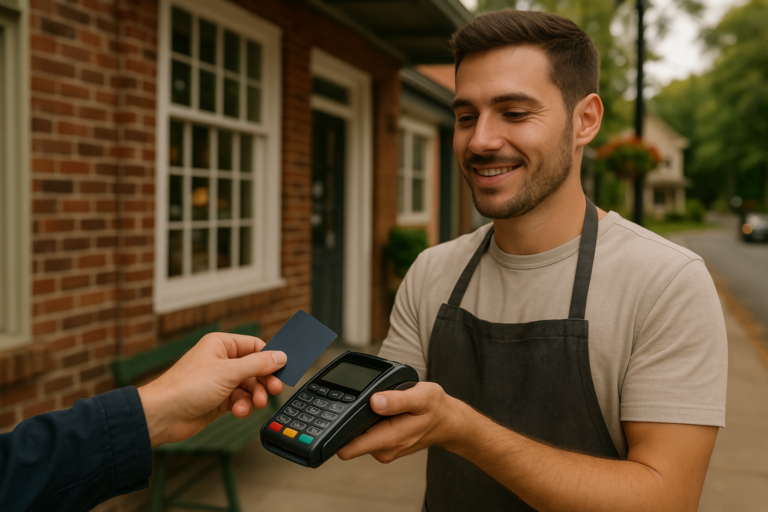
Frequently Asked Questions About Credit Card Processing in Country Lake Estates, New Jersey
What options are available for credit card processing for local businesses?
Credit card processing usually comes in a few common setups: countertop card readers, mobile/tap-to-pay solutions, and integrated point-of-sale systems. Many providers also support online payments for invoices or e-commerce. The best choice depends on how you take payments—at the register, at events, or remotely—and how many transactions you process monthly. Ask about device compatibility, payment types (credit/debit, contactless), and whether online payments are included in your setup.
How do credit card processing fees work?
Credit card fees typically include a combination of processing rates, network charges, and a monthly account or service component. Fees may vary based on card type (credit vs. debit), transaction method (swipe/tap/online), and your average ticket size. The clearest way to understand your cost is to request a fee schedule or sample statement showing the line items. Also ask how refunds, chargebacks, and tips are handled, since those can affect final totals.
Will my business still be able to accept contactless payments and mobile wallets?
In most modern processing systems, contactless payments (tap-to-pay) and major mobile wallets are supported through compatible terminals or payment integrations. The key is confirming that your specific device supports NFC/contactless and that your merchant account is configured to allow those payment types. If you already use certain equipment, ask whether it can be updated or whether you’ll need a new terminal or POS integration. This helps avoid surprises at checkout.
What should we do if a customer disputes a transaction (chargeback)?
When a chargeback happens, your processor typically provides a workflow for responding with documentation, such as receipts, authorization details, and any proof of delivery or service. The most important step is having clear recordkeeping from the start: consistent transaction records, accurate refund policies, and staff procedures that reduce errors. Ask your provider what information they require and how the dispute process is communicated, so you can respond promptly and appropriately.
How can we keep customer card data secure during everyday transactions?
To protect customer data, you should follow PCI-aligned practices, which often include using approved terminals and encryption-enabled processing so card details aren’t stored in unnecessary places. You can also reduce risk by keeping software updated, using secure Wi‑Fi or connectivity for online terminals, and limiting employee access to payment systems. When choosing processing equipment, ask how card data is handled end-to-end and what security responsibilities your business must follow for compliance.